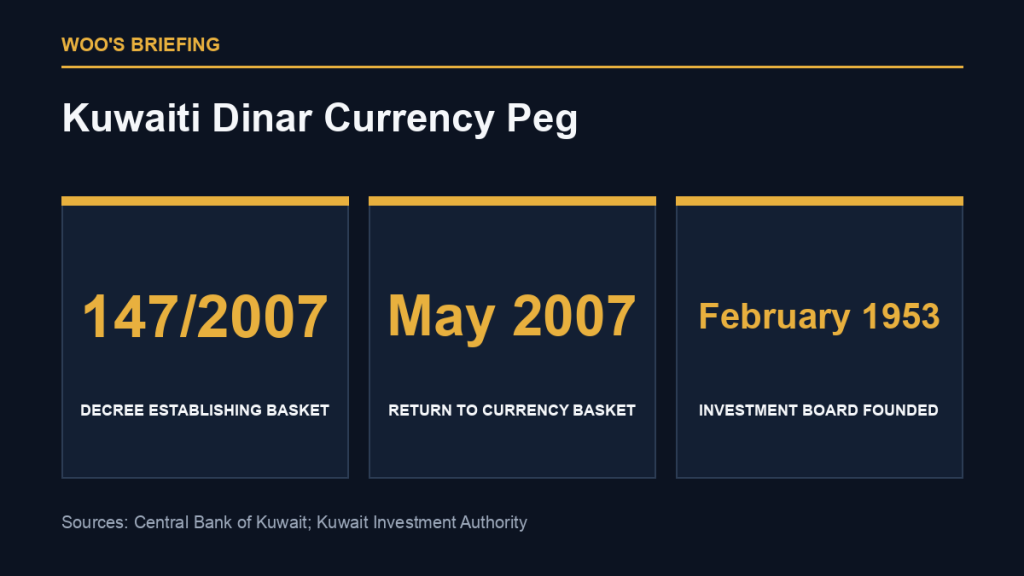
The Kuwaiti dinar currency basket is the anchor of Kuwait’s exchange rate: since 20 May 2007 the dinar has been tied to an undisclosed mix of currencies. The same instinct to shield a one-commodity economy led Kuwait to set up an investment board in London in February 1953, which the Kuwait Investment Authority calls the world’s first sovereign wealth fund.
Last updated: 2026-10-29
Key takeaways
- The Kuwaiti dinar has been pegged to an undisclosed weighted basket since 20 May 2007, under Decree No. 147/2007.
- The Central Bank of Kuwait says it moved back to the basket after long US dollar weakness, to protect purchasing power and contain inflation.
- Kuwait set up the Kuwait Investment Board in London in February 1953 to invest surplus oil revenue.
- The Kuwait Investment Authority calls itself the world’s first sovereign wealth fund.
What the Kuwaiti dinar currency basket is
A currency peg fixes one currency to another, or to a group of them. Kuwait does not fix the dinar to a single currency. Since 20 May 2007, under Decree No. 147/2007, the Kuwaiti dinar has been pegged to an undisclosed weighted basket of the currencies of Kuwait’s main trade and financial partners, according to the Central Bank of Kuwait.
The word to hold on to is “undisclosed”. The central bank does not publish which currencies are in the basket or what weight each one carries. Readers outside the region sometimes assume a Gulf peg means a dollar peg. For Kuwait, the public record says otherwise: the anchor is a mix, and the mix is not published.
A basket peg works in a simple way. The central bank keeps the dinar’s value against a weighted average of other currencies rather than against one. When one of those currencies strengthens, the dinar weakens a little against it and gains a little against the others, so it moves less against any single partner than it would under a one-currency peg. Because Decree No. 147/2007 ties the basket to Kuwait’s main trade and financial partners, the exchange rate follows the country’s actual commerce rather than one bilateral rate.
Why the central bank returned to the basket
The central bank gives its reason plainly: it returned to the basket after long US dollar weakness against major currencies, to protect the dinar’s purchasing power and contain inflation.
That explanation ties the exchange rate to prices at home. A country that imports much of what it consumes feels a weaker currency directly, as higher prices for those imports. The central bank states that its exchange rate policy aims to keep the dinar relatively stable and shield the economy from imported inflation.
So the peg is not only about the number on a screen. It is a tool aimed at the cost of goods coming into the country. The basket, rather than a single currency, is meant to spread that exposure across the partners Kuwait actually trades and banks with.
The 1953 fund in London
Kuwait’s other old financial choice points the same way. In February 1953 Kuwait set up the Kuwait Investment Board in the City of London to invest surplus oil revenue and reduce reliance on a single finite resource, according to the Kuwait Investment Authority.
A sovereign wealth fund is a state-owned pool of money invested for the long term, usually fed by commodity revenue or foreign exchange reserves. The Kuwait Investment Authority describes itself as the world’s first sovereign wealth fund, and says that its predecessor was at the time the only one.
The date matters for context: the board was set up in London in February 1953. The two choices, a basket peg and an overseas fund, sit at opposite ends of the same problem. One manages the value of the money coming in. The other puts part of it to work abroad so that a single finite resource does not carry the whole economy.
Why it matters: one commodity, two buffers
Read together, the two choices answer the same problem. An economy that leans on one finite resource faces two kinds of risk: the price of what it sells, and the price of what it buys. The fund addresses the first by holding assets beyond the resource. The peg addresses the second: the central bank says its policy is meant to shield the economy from imported inflation.
For readers watching Gulf currencies, the Kuwaiti dinar currency basket is the outlier to keep in mind. The undisclosed basket means the central bank maintains exchange rate policy without publishing partner weights, keeping the anchor tied to trading partners while shielding domestic purchasing power.
The fund side carries a similar logic of distance. One reading is that placing the board in London kept the money outside the domestic economy and its immediate risks.
What is not known, and what to watch
Official disclosures leave clear gaps. The central bank does not disclose the currencies in the basket or their weights, so the composition of the Kuwaiti dinar currency basket cannot be stated from the public record. The decree number and the date are known; the contents are not.
On the fund side, the facts cover the 1953 founding and the institution’s own description of itself. They do not give current assets, returns or holdings, so no figure for the fund’s size belongs in this piece.
What to watch: any central bank statement that explains a change in the peg’s mechanics, and any official update on how the investment authority presents its history and role. Until then, the outline is clear: Kuwait ties its currency to a mix it does not publish, and it has invested oil money abroad since 1953 to lessen its reliance on a single finite resource.